The UK’s water sector is experiencing mounting financial strain, highlighting broader risks for infrastructure sectors.
The sector urgently needs increased investment due to a combination of aging infrastructure, rising environmental pressures, and stricter regulatory requirements. At the same time, gearing ratios in the sector have continued to rise for two decades, so equity must be the marginal source of financing due to already exhausted balance sheets [See A Step change in UK infrastructure].
Ofwat has responded, by doubling expenditure allowances to £109bn for AMP8 (2025-2030), and increasing the allowed weighted average cost of capital (WACC). However, if these incentives do not attract sufficient equity investment, the sector could spiral into a doom loop—where rising costs and underinvestment lead to deteriorating service quality, higher consumer costs, and increased financial instability.
Show the data as a table
| From | To | |
|---|---|---|
| CoC | Investment | No new equity investment |
| Investment | Asset health | Worse consumer outcomes |
| Asset health | CoC | Higher risk |
1 WACC does not reflect equity risks and puts stress on highly geared balance sheets
2 Underinvestment, insufficient to maintain asset health
3 Poorer outcomes for consumers and the environment
4 Higher equity risk from diminishing performance and over-gearing
PR24: Further details
The UK’s water sector is the first regulated industry to significantly expand its capital program under PR24, reflecting urgent investment needs. However, financing this investment is increasingly complex due to high gearing ratios and rising interest rates. The sector’s debt-to-equity ratio has climbed over the past two decades, making it more vulnerable to economic and regulatory shocks, while making further fundraising reliant on equity.
In response, Ofwat has introduced:
- A doubling of allowed investment from £51bn (PR19) to £109bn (PR24).
- Higher maximum performance penalties, increasing from £1.44bn to £2.27bn.
- A higher WACC, rising from 2.96% (PR19) to 4.03% (PR24), reflecting new market conditions.
Despite these measures, structural risks remain. The water sector may be trapped in a negative feedback loop if:
- Cost of equity (CoE) does not accurately reflect future risks, under-incentivizing equity investors
- Under-investment, leading to worsening asset conditions and service disruptions
- Consumer outcomes decline, as operational failures increase
- Equity risk rises, reinforcing financial instability and making future equity financing even more unattractive
These issues are not confined to water alone. Other regulated infrastructure sectors, such as energy and rail, face similar investment challenges. With Ofgem’s RIIO-T3 (2026) and RIIO-ED3 (2027), and ORR’s PR8 (2027) on the horizon, these sectors must prepare for potential regulatory and financial recalibrations.
More research
A step-change in UK infrastructure investment
UK infrastructure investment is set to surge by 63% to £169bn (2025–2030), but balance sheets are already exhausted with debt
Cassandra Etter-Wenzel
1 min read
What capital will fund, what the system needs
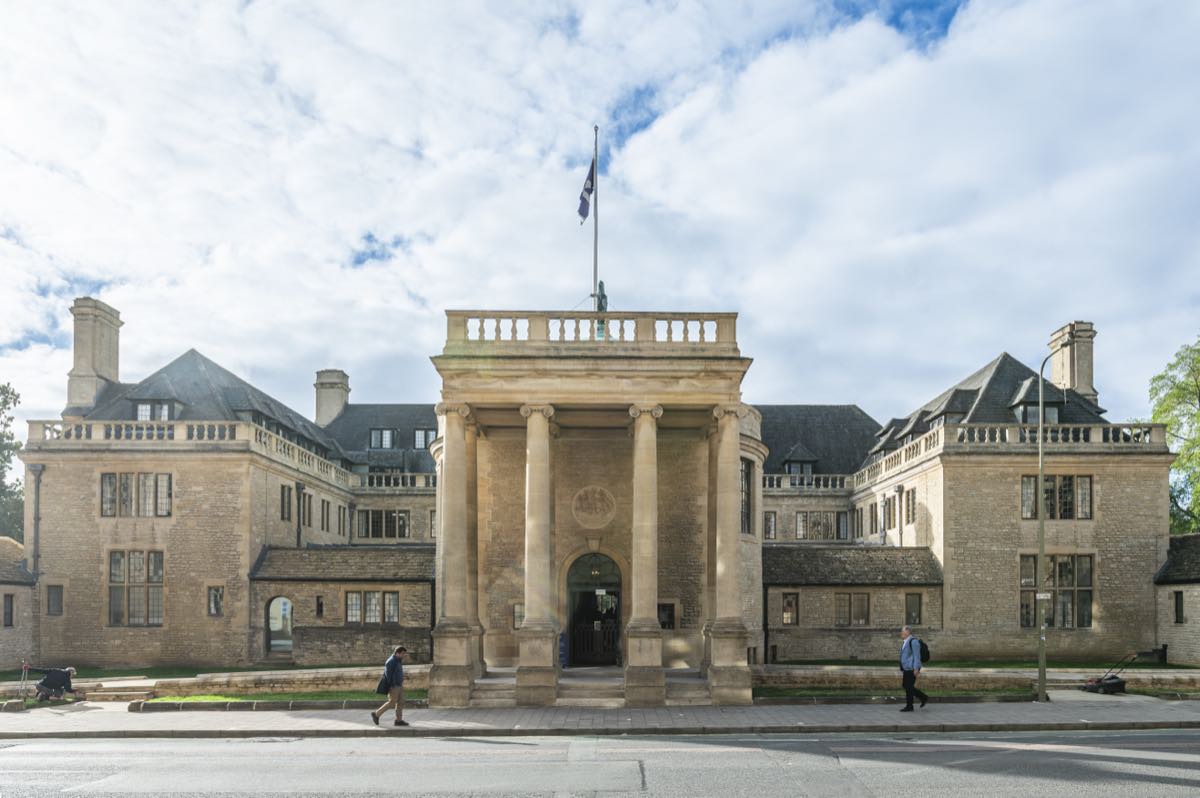
On 9 September 2026 we held the inaugural Vallorii Infrastructure Forum at Rhodes House, Oxford. 40 senior leader guests from government, regulators, utilities, investors and banks spent the day on one question: What will it take to make UK infrastructure fit for 2035, when the capital to build it exists but the certainty investors need before they commit it does not? The day had four panel sessions – macro risk, delivery, maintenance and valuation – as well as keynotes by Minister for...
Gaia Guadagnini
7 min read