Capital expenditure in key UK infrastructure sectors (water, rail, electricity transmission and distribution) is set to increase by 63%, rising from £103bn (2020–2025) to £169bn (2025–2030).
The marginal source of capital is equity because balance sheets are exhausted after many decades of debt finance. Leverage is particularly high in the water sector in particular is highly leveraged, with net debt reaching £69bn and gearing ratio averaging 70%, limiting its ability to raise further debt.
Equity investment needs thus face a step-change, increasing by over £120bn in water, rail, electricity transmission, and electricity distribution alone. Without sufficient investment, there is a risk of underfunding critical projects, leading to long-term service quality issues, failure to decarbonize the energy system, and increased consumer costs resulting from deteriorating asset health.
Projection: > 63% capex growth
- Elec. Transmission
- Elec. Distribution
- Rail
- Water & Wastewater
2020–2025103
Elec. Transmission 7 · Elec. Distribution 11 · Rail 55 · Water & Wastewater 29
2025–2030169
Elec. Transmission 33 · Elec. Distribution 13 · Rail 63 · Water & Wastewater 60
Show the data as a table
| Elec. Transmission | Elec. Distribution | Rail | Water & Wastewater | ||
|---|---|---|---|---|---|
| 2020–2025 | 7 | 11 | 55 | 29 | 103 |
| 2025–2030 | 33 | 13 | 63 | 60 | 169 |
Balance sheets are fully leveraged in water
In the past 20 years, debt has been the marginal source of finance in many regulated infrastructure sectors. As a result, companies, particularly in the water sector, are highly geared. Net debt across water companies currently stands at ~£69 billion, with gearing ratios averaging ~70%.
Current Gearing ratios – companies regulated by Ofwat (%)
- Gearing 2024
- Gearing 2023
- Dashed reference line
Schematic based on the original figure
To finance capital projects, companies must raise new equity. This is particularly challenging in today’s environment due to high interest rates and international competition for capital. Is the current regulatory framework fit to support these investment decisions?
More research
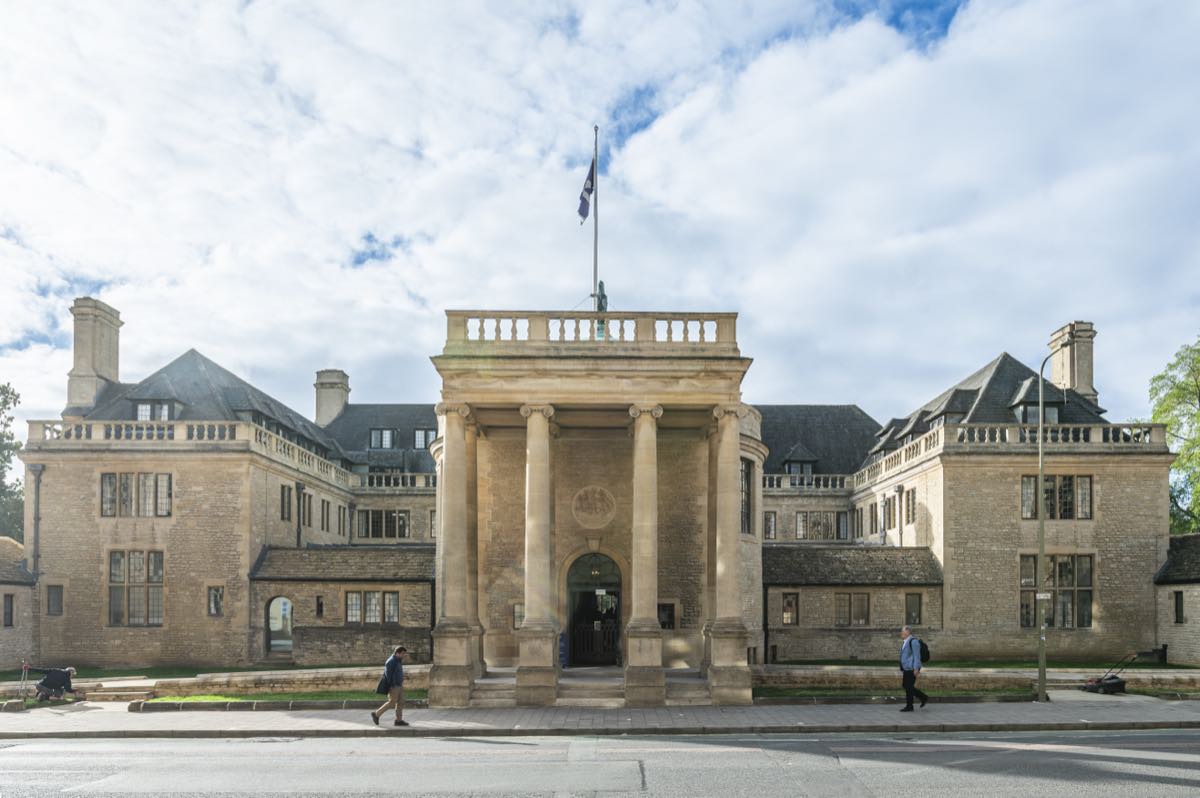
What capital will fund, what the system needs
On 9 September 2026 we held the inaugural Vallorii Infrastructure Forum at Rhodes House, Oxford. 40 senior leader guests from government, regulators, utilities, investors and banks spent the day on one question: What will it take to make UK infrastructure fit for 2035, when the capital to build it exists but the certainty investors need before they commit it does not? The day had four panel sessions – macro risk, delivery, maintenance and valuation – as well as keynotes by Minister for...
Gaia Guadagnini
7 min read
Thematic Report: VAPRI: Vallorii's Price of Risk model for infrastructure cost of equity
CAPM has been the workhorse model for cost of equity across regulated utilities but is reaching its limits.
Vallorii
2 min read